Turning 65? Transitioning to Medicare: Your First Steps Explained
If you're turning 65 in the next few months, your first step is to activate Medicare Part A and Part B through Social Security — ideally about 90 days before your birthday. Here's exactly what to do, what arrives in the mail, why Original Medicare alone isn't enough, and why speaking with a licensed insurance broker who has a teaching spirit makes all the difference.
John Dennis, Theology MA, MBA, Biology BA — AliveInsure.com
Health, Medicare & Life Insurance Broker
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Not connected with or endorsed by the U.S. government or the federal Medicare program.
We represent Medicare Advantage organizations and standalone PDP prescription drug plans that have a Medicare contract. Enrollment depends on the plan's contract renewal. Calling (407) 815-0820 will connect you to a licensed sales agent. TTY: 711.
So you're turning 65 in the next few months — congratulations. This is one of the most important transitions in your healthcare life, and getting it right from the start can save you thousands of dollars and a lot of stress. The good news is that the process is straightforward once you know the steps. The better news is that you don't have to figure it out alone. Here is exactly what to do, in the right order, so there are no unexpected surprises.
Step 1 — Activate your Medicare Part A and Part B through Social Security. Your very first move is to contact the Social Security Administration (SSA), because Social Security handles Medicare enrollment — not your doctor, not your employer, and not an insurance company. You can sign up online at ssa.gov/medicare/sign-up, or you can call Social Security at 1-800-772-1213 (TTY 1-800-325-0778 if you're deaf or hard of hearing). Representatives are available in most U.S. time zones Monday through Friday, 8 a.m. to 7 p.m., in English, Spanish, and other languages. Tell the representative you want to sign up for Medicare Parts A and B (or Part A only if you're still working and covered by an employer plan). I recommend doing this about 90 days before your 65th birthday so everything is in place on day one.
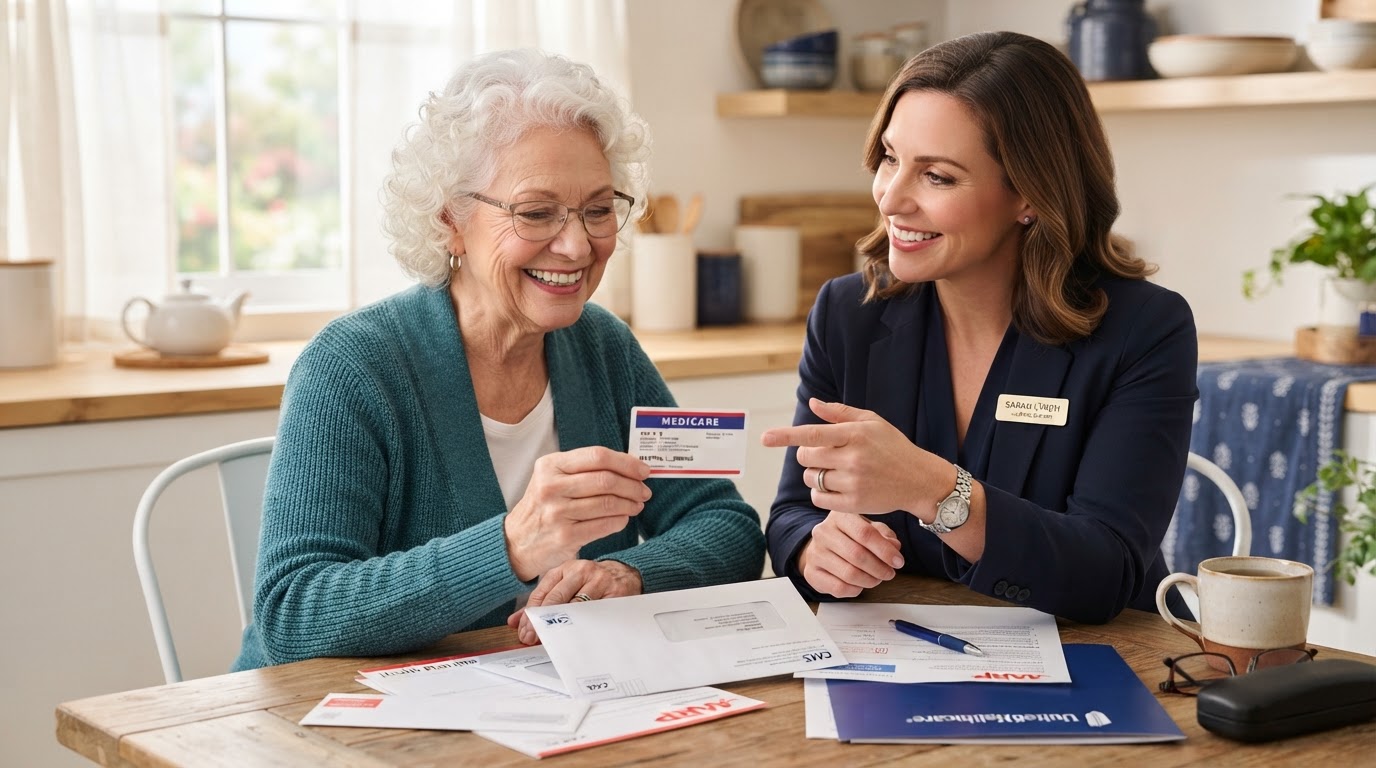
Step 2 — Watch for your Medicare card in the mail. Once Social Security processes your enrollment, your red, white, and blue Medicare card should arrive in the mail about 90 days before you turn 65 (when you enroll on time). Open it right away and confirm that your name, Medicare number, and Part A and Part B effective dates are all correct. If anything looks wrong — a misspelled name, a wrong start date, a missing part — call Social Security back immediately. Small errors now can cause big headaches later, so make sure everything is okay before you move on.
Step 3 — Understand what you actually have. Once your Medicare ID is active, you have what's called Original Medicare — Part A (hospital coverage) and Part B (medical and doctor coverage). But here's what most people don't realize: Original Medicare by itself does NOT include prescription drug coverage, and it leaves you responsible for the 20% coinsurance on Part B services with no cap on your out-of-pocket costs. There is no maximum out-of-pocket limit on Original Medicare alone. That 20% gap — plus the cost of your medications — is exactly where adding either a Medicare Supplement (Medigap) plan or a Medicare Advantage plan comes in to fill the gap.
Step 4 — Fill the gap with a Supplement or Advantage plan. A Medicare Supplement (Medigap) plan works alongside Original Medicare and helps pay the 20% coinsurance, deductibles, and copayments that Original Medicare leaves behind — giving you predictable costs and the freedom to see any doctor who accepts Medicare nationwide. A Medicare Advantage plan replaces Original Medicare's gap coverage with a single bundled plan that often includes prescription drug coverage, dental, vision, and extras, usually with a $0 or low premium but with network restrictions and a maximum out-of-pocket limit. The right choice depends on your doctors, your medications, your budget, and whether you travel. This is exactly where a licensed insurance broker becomes invaluable.
Step 5 — Talk to a licensed insurance broker who has a teaching spirit. This is the step I cannot emphasize enough. You are making decisions that affect your healthcare and your wallet for the rest of your life — and the options are genuinely complex. Find a broker who doesn't just sell, but who clearly explains each plan option in plain language, answers your detailed questions patiently, and helps you understand the trade-offs. A good broker compares every plan available in your area from multiple carriers, not just one, so the recommendation fits you — not a sales quota. Make sure they are licensed and can provide their National Producer Number (mine is 17808176, and you can verify any broker the same way).
What if you have End-Stage Renal Disease (ESRD)? There is a special path. If you have ESRD (permanent kidney failure requiring dialysis or a transplant), you can get Medicare regardless of age. Call 1-800-772-1213 and tell the representative you want to apply for Medicare because you have ESRD. They will guide you through the special enrollment process. The same phone line and hours apply — Monday through Friday, 8 a.m. to 7 p.m., in English, Spanish, and other languages. You can also make an appointment through the Social Security website at ssa.gov/medicare/sign-up.
A few important reminders so there are no surprises. First, enroll during your Initial Enrollment Period — the 7-month window that begins 3 months before the month you turn 65, includes your birthday month, and ends 3 months after. If you miss this window without other coverage, you may face permanent late-enrollment penalties. Second, if you're still working and covered by a group health plan at 65, you may be able to delay Part B without a penalty — but talk this through with a broker first, because the rules depend on your employer's size. Third, never give your Medicare number to an unsolicited caller offering 'free' cards or cash — that's fraud.
The bottom line: turning 65 is exciting, and transitioning to Medicare should feel empowering, not overwhelming. Activate Part A and Part B through Social Security about 90 days early, confirm your card is correct, understand that Original Medicare alone leaves a 20% gap and no drug coverage, and then sit down with a licensed insurance broker who has a teaching spirit to choose the Supplement or Advantage plan that fits your life. As an independent licensed insurance broker serving families in 28 states — and connecting customers in all 50 to trusted coverage — I'd be honored to walk you through every option. Call me at (407) 815-0820 or book a free consultation below, and I'll make sure your Medicare transition is smooth, clear, and completely on your terms.
Ask a Question About this Article or Suggest an Article to Write
Have a question about what you just read, or an insurance topic you'd like John to write about next? Send it to John and he'll personally reply with expert, no-pressure guidance.
Turning 65 soon? Let's get your Medicare right the first time.
I'll walk you through activating Part A and Part B, confirm your card is correct, and compare every Supplement and Advantage plan in your area — clearly, patiently, and with no pressure. Book a free consultation with John Dennis, independent licensed insurance broker.
Have questions about this topic?
Book a free, no-pressure consultation with John Dennis, independent licensed insurance broker.
Book an appointment