Surprise Medical Bills Explained: Your Rights Under the No Surprises Act & How to Protect Yourself
You went to an in-network ER and still got a bill from an out-of-network doctor. That's balance billing — and federal law now protects you from most of it. Here's exactly what to do before, during, and after a hospital visit.
John Dennis, Theology MA, MBA, Biology BA — AliveInsure.com
Health, Medicare & Life Insurance Broker
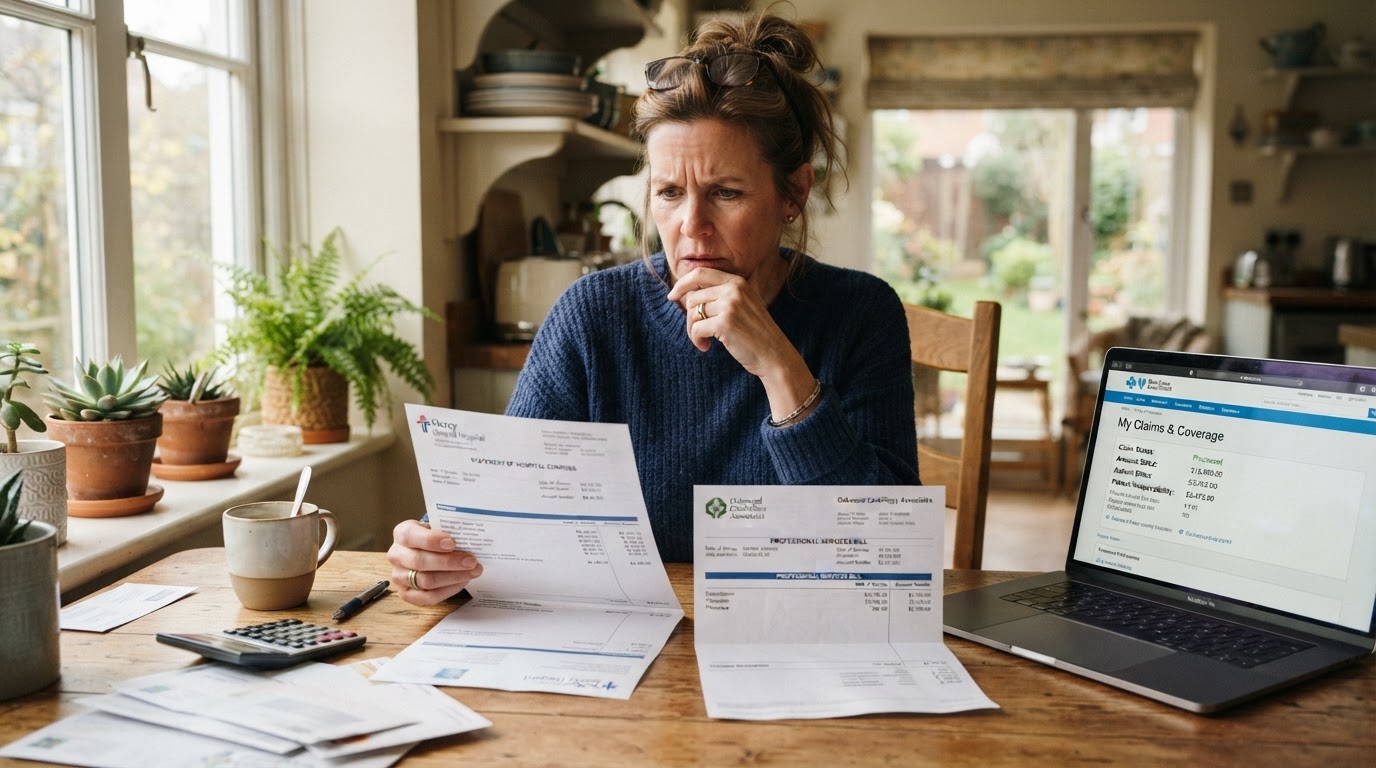
A real story I hear all too often: a customer goes to an in-network emergency room — one their insurance plan covers — and weeks later receives not one bill, but two. The first is from the hospital, processed in-network as expected. The second is from a group of doctors — emergency physicians, anesthesiologists, radiologists, or pathologists — who are not in their insurance network, even though they work inside that same in-network hospital. That second bill can be thousands of dollars, and it arrives with no warning. This is called surprise billing, or balance billing, and it is one of the most frustrating experiences in American healthcare.
Here is how it happens. When you receive care at an in-network hospital, you reasonably assume everyone treating you is also in-network. But many hospitals contract with independent physician groups to staff their emergency departments, operating rooms, and radiology suites. Those physician groups may not accept your insurance, even though the hospital does. The doctor's group bills your insurer, the insurer pays its in-network rate, and the doctor 'balances' the remaining amount onto you — hence the name balance billing. You had no way to choose these doctors, no way to verify their network status mid-emergency, and no way to refuse their care. Yet you are left holding the bill.
The good news: federal law changed this. The No Surprises Act, which took effect on January 1, 2022, protects you from most surprise balance bills. Under the law, you cannot be balance-billed for emergency services from out-of-network providers or facilities, or for non-emergency services performed by out-of-network doctors at an in-network facility (like an anesthesiologist or assistant surgeon at an in-network hospital). Instead, your insurer must treat those services as if they were in-network, and any cost-sharing you owe is based on the in-network rate. The provider and insurer are then required to work out the payment difference between themselves — not through you.
What are your rights under the No Surprises Act? First, you have the right to emergency services without prior authorization from your insurer, regardless of whether the facility or provider is in-network. Second, you cannot be charged more than the in-network cost-sharing amount (copay, coinsurance, deductible) for emergency services. Third, out-of-network providers at in-network facilities cannot send you a balance bill for services you did not knowingly choose — this covers anesthesiologists, pathologists, radiologists, surgical assistants, and hospitalists. Fourth, if there is a payment dispute between the provider and your insurer, it must be resolved through an independent dispute resolution process — you are not the middleman and you should not be dragged into it.
There are important exceptions to know. The No Surprises Act does not protect you if you knowingly and voluntarily choose an out-of-network provider for non-emergency care. In those situations, the provider must give you a good faith estimate of the charges and a consent form at least 72 hours before the service. If you sign that consent, you can be balance-billed — so read carefully before signing anything that mentions 'out-of-network' or 'balance billing.' The law also does not apply to ground ambulance services in most states, which remains a significant gap, though some states have their own protections. It does not apply to plans that are not regulated by the ACA, such as short-term limited-duration plans or certain faith-based health sharing ministries.
So how do you prepare before a hospital visit? Start by understanding your plan's network — but recognize its limits. You can verify that a hospital is in-network, but you often cannot verify every individual doctor who will treat you inside that hospital, especially in an emergency. That is exactly the gap the No Surprises Act fills. For planned procedures, ask the facility for a list of every provider who will be involved — surgeon, anesthesiologist, pathologist, radiologist — and verify each one against your insurer's network directory. Request a good faith estimate of costs in advance. If any provider is out-of-network, ask whether an in-network alternative is available, and do not sign a consent form for out-of-network care unless you understand the full financial exposure.
What should you do if a surprise bill arrives despite the law? Do not panic, and do not pay it immediately. Here is the step-by-step: First, call your insurer and confirm whether the service is covered under the No Surprises Act protections. Ask them to process the claim at the in-network rate. Second, if the provider continues to bill you for the balance, request a formal explanation of benefits from your insurer and a itemized bill from the provider. Third, file a complaint. You can submit a complaint to the federal government through the Centers for Medicare & Medicaid Services No Surprises Act complaint portal, and to your state's department of insurance — in Florida, that is the Office of Insurance Regulation. Fourth, if the dispute is about the payment amount between the provider and insurer (not your cost-sharing), that goes to independent dispute resolution, and you should not be billed during that process. Fifth, keep every document — bills, EOBs, correspondence — organized by date.
It is also worth knowing that many hospitals and health systems are required to post a notice explaining your protections under the No Surprises Act. For example, AdventHealth publishes a No Surprises Act notice for Florida patients that summarizes your rights and how to file a complaint. I recommend downloading and reading your local hospital's notice before you need it, so you understand your rights in advance. You can view a sample notice here.
The deeper lesson: the American healthcare billing system is deliberately complex, and the only real protection is a combination of knowing your rights and having the right coverage in place. A well-chosen health insurance plan — whether ACA Marketplace, Medicare Advantage, Medicare Supplement, or a private plan — sets your maximum out-of-pocket limit and gives you a network and an appeals process to fight back. If you are uninsured or underinsured, a surprise bill can be financially devastating; with proper coverage, your exposure is capped and the No Surprises Act gives you a legal shield for the most common scenarios.
If you have received a surprise bill, or you want to make sure your current plan protects you before an emergency happens, I can help. As an independent licensed insurance broker, I review plans across multiple carriers to find one with strong network coverage, reasonable out-of-pocket limits, and the protections that matter most for your situation. Call me at (407) 815-0820, compare plans through the link below, or book a free consultation — and I will walk through your coverage and your rights so a surprise bill never catches you off guard again.
Ask a Question About this Article or Suggest an Article to Write
Have a question about what you just read, or an insurance topic you'd like John to write about next? Send it to John and he'll personally reply with expert, no-pressure guidance.
Make sure your plan protects you from surprise bills
Review your health coverage with John Dennis, independent licensed insurance broker, to confirm your network, out-of-pocket limits, and No Surprises Act protections — before an emergency happens.
Have questions about this topic?
Book a free, no-pressure consultation with John Dennis, independent licensed insurance broker.
Book an appointment