Your Newborn Is Covered Under Mom's Health Insurance for 60 Days — Here's What to Expect
When your baby is born, they're automatically covered under the mother's health plan for the first 60 days. But to keep that coverage, you'll need the baby's Social Security number — which arrives in the mail days later. Here's the timeline and what parents should expect.
John Dennis, Theology MA, MBA, Biology BA — AliveInsure.com
Health, Medicare & Life Insurance Broker
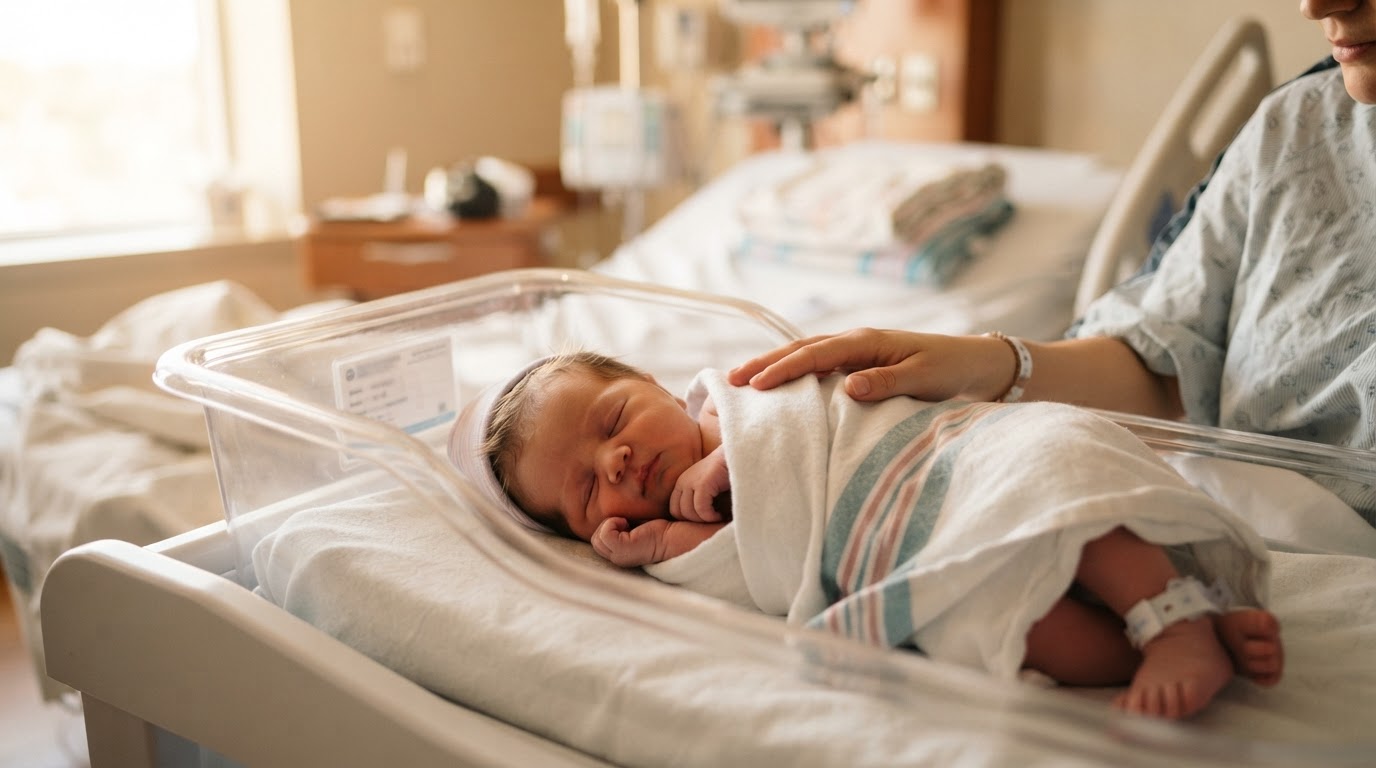
One of the most common questions I get from expecting parents is simple but important: how do I add my new baby to my health insurance? The good news is that the system is designed to protect newborns. Under federal law, when a baby is born, they are automatically covered under the mother's health insurance plan for the first 60 days of life. You do not need to do anything for those first 60 days — the baby is covered as a dependent under the mother's policy for routine newborn care, the hospital stay, and any medically necessary care during that window.
But here is the catch that catches many parents off guard: that automatic 60-day coverage is temporary. To keep your baby on the plan beyond day 60, you must formally add the child to the policy as a dependent. And to do that, the insurance company requires the baby's Social Security number. That is where the timeline gets tricky, because the Social Security number is not issued at the hospital — it arrives in the mail several days, sometimes a couple of weeks, after the birth. So you have a 60-day clock ticking, and a document you cannot control the arrival of.
Here is exactly what I recommend you do. First, the moment your baby is born, contact me — your independent licensed insurance broker — and let me know. I will start the paperwork and open the enrollment change so that everything is ready. This is a qualifying life event under the Affordable Care Act, which means you have a special enrollment period to add the baby to your Marketplace plan, your employer-sponsored group plan, or your private plan. The window is 60 days from the date of birth, and I will help you meet it.
Second, apply for your baby's Social Security number right away. The hospital will typically help you complete the application as part of the birth registration process — you do not usually need to go to a Social Security office. The card is then mailed to you, generally within one to two weeks, though it can occasionally take longer. The moment that card arrives, send me the number. I will submit it to the insurance carrier to finalize adding your child to the policy before the 60-day deadline.
Third, do not wait until day 55 to start this process. If the Social Security card is delayed in the mail and you miss the 60-day window, your baby could lose coverage and you may have to wait until the next open enrollment period — which could be months away — to add them back. That is a gap no parent wants, especially with a newborn who needs well-baby visits, vaccinations, and pediatric checkups. Start early, keep me informed, and we will keep the timeline on track.
Now, what about the bills? Parents are often surprised to learn that the hospital may issue separate charges for the baby that are medically necessary and distinct from the mother's delivery charges. For example, if your newborn needs time in the neonatal intensive care unit (NICU), special monitoring, jaundice treatment under phototherapy lights, a circumcision, treatment for low blood sugar, or evaluation by a pediatric specialist, those services are billed under the baby's name — not the mother's. During the first 60 days, those charges are covered under the mother's plan, but after the baby is formally added, they are covered under the baby's own policy. Either way, you may see separate line items and separate explanation-of-benefits statements for the baby's care, and that is completely normal.
It is also important to understand your cost-sharing. Even though the baby is covered, you may still be responsible for copays, coinsurance, or deductible amounts that apply to the baby's care, depending on your plan. If your plan has a family deductible, the baby's charges may help meet it. If you have a high-deductible health plan paired with an HSA, this is a good time to use those HSA funds. And if your newborn has any complications that require extended hospitalization, reaching your plan's out-of-pocket maximum can protect you from runaway costs — another reason to make sure the baby is properly enrolled before the 60-day window closes.
What if the mother and father are on different plans? The baby can be enrolled on either parent's plan, and in many cases you can choose. Some families add the baby to the plan with the better pediatric network or lower cost-sharing. If both parents have employer-sponsored coverage, the 'birthday rule' typically applies — the plan of the parent whose birthday falls earlier in the calendar year is the primary plan for the child. I can help you compare both options and decide which makes the most financial sense for your family.
If you are uninsured or your current plan does not cover maternity or newborn care well, the birth of a child is also a qualifying life event to enroll in a new ACA Marketplace plan — even outside of open enrollment. This is one of the most important moments to get professional guidance, because the right plan chosen at the right time can save your family thousands of dollars in the first year of your baby's life alone.
The bottom line: your newborn is protected for the first 60 days under the mother's plan, but keeping that protection depends on a simple but time-sensitive step — adding the baby to the policy with their Social Security number before day 60. Call me the day your baby is born. I will handle the paperwork, track the deadline, and make sure your child is enrolled the moment that Social Security card arrives. As an independent licensed insurance broker, I help families across 28 states get this right — so you can focus on your new baby, not the paperwork. Reach me at (407) 815-0820 or book a free consultation through the link below.
Ask a Question About this Article or Suggest an Article to Write
Have a question about what you just read, or an insurance topic you'd like John to write about next? Send it to John and he'll personally reply with expert, no-pressure guidance.
Adding your newborn to your health plan? Let's get it right.
The 60-day window closes fast. Contact John Dennis, independent licensed insurance broker, to add your baby to your policy the moment their Social Security number arrives — and make sure your family has the right coverage from day one.
Have questions about this topic?
Book a free, no-pressure consultation with John Dennis, independent licensed insurance broker.
Book an appointment